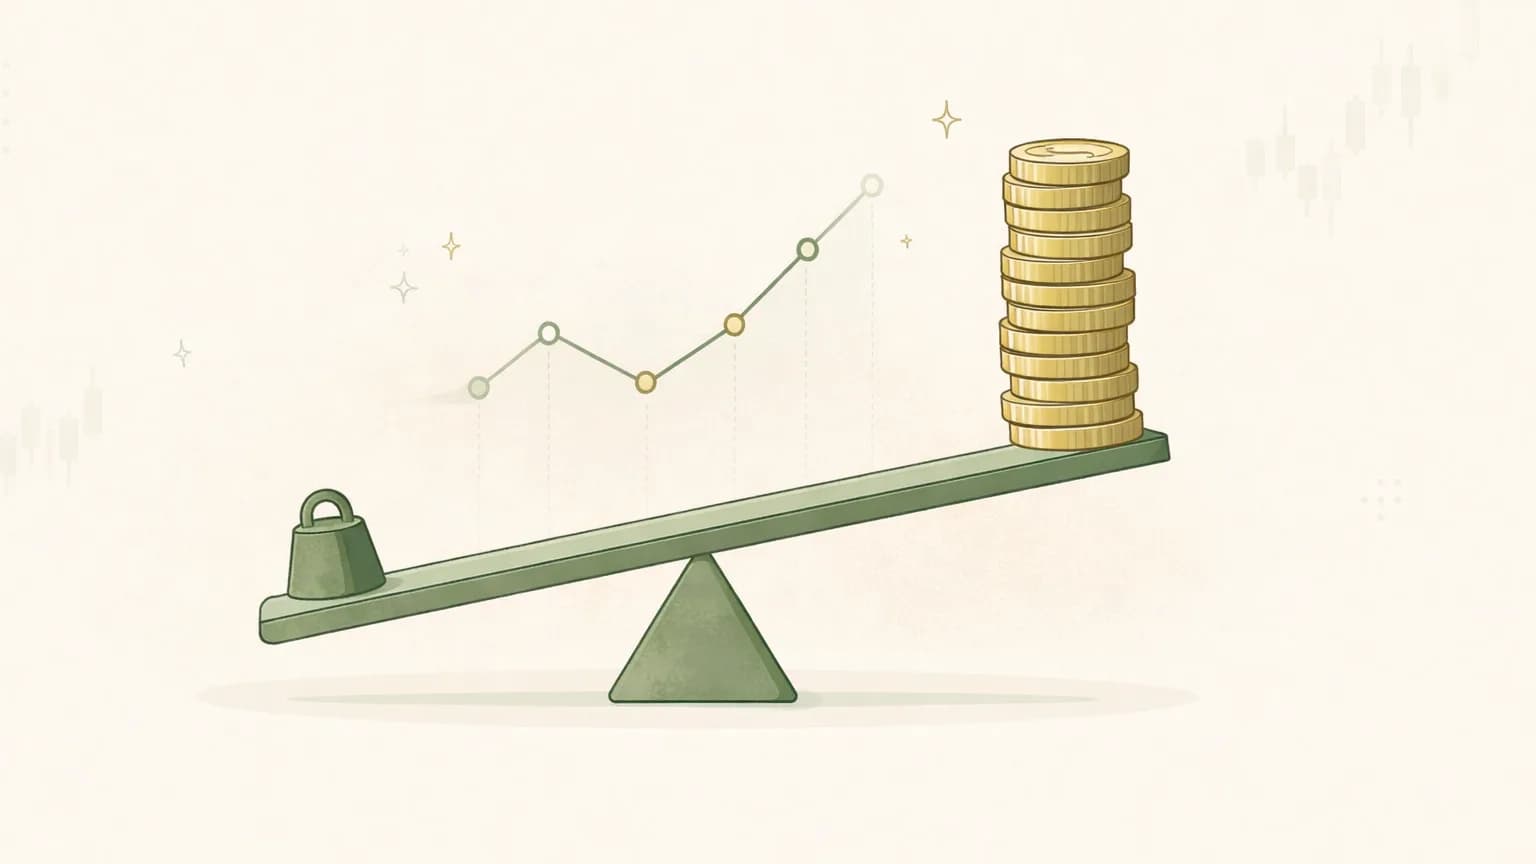
Two companies grow their sales 10% this year. One reports profit up 12%. The other reports profit up 35%. Same top-line growth, wildly different bottom lines — and the single biggest reason for the gap has a name: operating leverage.
Operating leverage is the reason a business can grow profits far faster than revenue on the way up — and bleed them far faster on the way down. It's baked into a company's cost structure long before any given quarter, and if you don't understand it, earnings reports will keep surprising you in both directions.
This guide explains what operating leverage actually is, walks through the math with a worked (illustrative) example, and shows you how to spot high- versus low-leverage businesses so you can read their numbers with the right expectations. No jargon you have to take on faith — just the mechanism and how to see it.
What operating leverage actually is#
Every company's costs fall into two buckets. Fixed costs stay roughly the same no matter how much you sell — factory rent, salaried engineers, the software platform, the depreciation on equipment you already bought. Variable costs rise and fall with sales — raw materials, shipping, payment processing, the cost of each additional unit.
Operating leverage is simply how heavily a business leans on fixed costs. A company with a big fixed-cost base and low variable costs has high operating leverage. A company whose costs mostly move with sales has low operating leverage.
Here's why that matters. When fixed costs dominate, every extra dollar of revenue costs very little to produce — so most of it falls straight through to operating profit. The company spends years covering that fixed base, and once sales clear it, additional revenue is disproportionately profitable. But the same rigidity works in reverse: when sales fall, the fixed costs don't shrink with them, so profit collapses faster than revenue does.
The number that captures this is the contribution margin — the share of each revenue dollar left after variable costs. A business with 70% contribution margin keeps 70 cents of every incremental dollar to put toward fixed costs and profit. A business with 30% keeps 30 cents. The higher that number, the more powerful the operating-leverage effect in both directions. (If contribution margin and its cousins are fuzzy, the Valarn glossary defines each one.)
The math, worked through#
Numbers make this concrete. The figures below are illustrative — round numbers chosen to show the mechanism, not a real company.
Take a high-fixed-cost business:
- Revenue: $100M
- Variable costs (30% of revenue): $30M
- Fixed costs: $50M
- Operating profit: $100M − $30M − $50M = $20M
Now grow revenue 10%, to $110M. Variable costs rise with sales to $33M, but fixed costs stay at $50M:
- Revenue: $110M
- Variable costs (30%): $33M
- Fixed costs: $50M (unchanged)
- Operating profit: $110M − $33M − $50M = $27M
Revenue rose 10%. Profit rose from $20M to $27M — a 35% jump. A 10% top-line gain produced a 35% bottom-line gain, because the extra $10M of revenue only carried $3M of new cost. The other $7M dropped straight to operating profit. That's operating leverage doing its work, and it's a big part of why earnings can grow faster than revenue at a scaling business.
The catch: it cuts both ways#
Here's the part the excited version of this story leaves out. Operating leverage is not a growth engine — it's an amplifier, and amplifiers don't care which direction the signal points.
Run the same company backward. Revenue falls 10%, to $90M. Variable costs drop to $27M, but the fixed $50M doesn't budge:
- Revenue: $90M
- Variable costs (30%): $27M
- Fixed costs: $50M (still unchanged)
- Operating profit: $90M − $27M − $50M = $13M
A 10% revenue decline just cut profit from $20M to $13M — a 35% drop, perfectly symmetric with the upside. The fixed costs that supercharged profit on the way up become an anchor on the way down, because they have to be paid whether the sales show up or not.
This is why high-operating-leverage companies can post ugly, alarming earnings misses on what looks like a modest sales dip — and it's one of the mechanical reasons a stock can fall even after a "good" earnings report: if revenue grew but slightly less than the market's fixed-cost-adjusted expectation, profit can miss badly. The reward and the risk are the same feature viewed from two sides.
High vs low operating leverage, side by side#
Now compare that high-leverage business to a low-leverage one starting from the same $20M profit — but built on mostly variable costs (70% of revenue) and a small $10M fixed base. Watch how differently the two respond to identical revenue moves:
| High operating leverage | Low operating leverage | |
|---|---|---|
| Variable costs | 30% of revenue | 70% of revenue |
| Fixed costs | $50M | $10M |
| Profit at $100M revenue | $20M | $20M |
| Profit if revenue +10% | $27M (+35%) | $23M (+15%) |
| Profit if revenue −10% | $13M (−35%) | $17M (−15%) |
| Character | Explosive, fragile | Steady, resilient |
(Illustrative figures.) Same starting profit, same revenue swings, completely different outcomes. The high-leverage business swings ±35% on a ±10% revenue move; the low-leverage business swings only ±15%. Neither is "better" — they're different risk-and-reward shapes, and which one suits a situation depends entirely on where the business is in its cycle and how stable its demand is.
Roughly speaking, these are the archetypes:
- High operating leverage: software, semiconductors, telecom networks, airlines, hotels, streaming, heavy manufacturing. Enormous upfront or fixed costs, cheap incremental units. Wonderful at scale, brutal when volumes fall.
- Low operating leverage: consulting, staffing, distribution, grocery retail, contract manufacturing. Costs track revenue closely, so margins are thinner and steadier — less operating upside, but far less operating cliff.
Degree of operating leverage#
If you want a single gauge, analysts use the degree of operating leverage (DOL): the percentage change in operating profit divided by the percentage change in revenue.
In the high-leverage example, profit moved 35% on a 10% revenue change, so DOL ≈ 3.5×. In the low-leverage example, 15% on 10% gives DOL ≈ 1.5×. A DOL of 3.5 means: for every 1% revenue moves, expect operating profit to move about 3.5% — up or down.
Two cautions. First, DOL isn't a fixed constant; it's highest when a company is barely above breakeven (fixed costs loom largest relative to profit) and flattens as the business scales far past that point. Second, it's a snapshot, not a promise — it describes the sensitivity built into today's cost structure, not a forecast of what revenue or profit will actually do.
Why operating leverage matters for your research#
Understanding a company's operating leverage changes how you read almost everything else about it.
- It sets your expectations for earnings surprises. A high-DOL business will beat big when demand runs hot and miss big when it cools. If you don't know the leverage is there, every quarter looks like a shock. If you do, the swings are the expected behavior of the machine.
- It reframes margins. Expanding operating margins at a high-leverage company often aren't a sign of new pricing power — they're just the fixed base getting spread over more revenue. That's a different, more mechanical story than a durable moat, and it's worth separating gross margin from operating margin to see which lever is actually moving.
- It reframes risk. The same fixed costs that make growth exhilarating make a downturn dangerous, especially if the company also carries a lot of debt (that's financial leverage — a separate amplifier that stacks on top of operating leverage; a business heavy in both is exposed on two fronts at once).
- It puts revenue trends in context. For a high-leverage company, the direction and consistency of revenue matters even more than the level, because profit is so sensitive to it. This is exactly why step-by-step research frameworks like our 12-step guide to researching a stock treat cost structure and margins as their own distinct steps rather than lumping them together.
How to spot it in the numbers#
You won't find "operating leverage" on a line of the income statement — you infer it. A few practical tells:
- Compare revenue growth to operating-profit growth over several years. If profit routinely grows two or three times faster than revenue in good years (and falls faster in bad ones), you're looking at meaningful operating leverage. If they move roughly in lockstep, leverage is low.
- Read the cost structure in the filings. The 10-K and 10-Q break costs into categories. A business dominated by depreciation, R&D, and salaried headcount is fixed-cost-heavy; one dominated by cost of goods that scales with each sale is variable-cost-heavy. A quick way to orient yourself on a specific name before you open the filing is a company research page.
- Watch behavior in a downturn. The cleanest real-world test is what happened to profit the last time revenue actually fell. Margins that cratered on a modest sales dip reveal high operating leverage more honestly than any ratio.
- Check where the company sits versus breakeven. A high-fixed-cost business that has only just cleared its fixed base is the most explosive — and the most fragile. The same business, years later and far past breakeven, behaves much more calmly.
Where Valarn fits in#
Operating leverage is one thread in a much larger picture — margins, cash flow, valuation, debt, competitive position, catalysts — and no single number captures it. That's the problem Valarn is built to work through as an educational research tool.
Instead of one AI handing you a confident paragraph, Valarn convenes up to about 25 specialist AI analysts across five categories — core research, market structure, debate and risk, financial quality, and events/sector/macro. A financial-quality analyst can examine how a company's fixed-versus-variable cost mix shapes its margin sensitivity; a fundamentals analyst reads the multi-year revenue-to-profit relationship; a dedicated risk committee weighs how that same leverage cuts on the downside. Then the analysts stage a formal bull-versus-bear debate and synthesize a single, neutral research view — Bullish, Cautious Bullish, Neutral, Cautious, or Bearish — never a buy or sell instruction.
The parts that make it checkable rather than merely fluent: every factual claim is traceable to a filing or licensed source with an as-of date; a quality-assurance gate runs before anything reaches you; and each report carries two 0–100 scores — a confidence score reflecting data quality (not a price prediction) and an agreement score measuring how much the analysts converged. Where a Wall Street price target would go, you get a Scenario Range (bear/base/bull) plus a Reference Price and a Risk Level, with the Street's own consensus reported separately as a third-party fact rather than blended into Valarn's view.
You can read a full sample report to see how the cost-structure and margin analysis is laid out, or run your own free research report and inspect the reasoning yourself.
The bottom line#
Operating leverage is why "revenue grew 10%" can mean profit soared 35% at one company and inched up 12% at another. It comes down to a single structural choice — how much of the cost base is fixed versus variable — and it amplifies results in both directions, turning modest sales gains into earnings leaps and modest sales dips into earnings collapses.
Understand a company's operating leverage and its earnings stop surprising you. High leverage means bigger rewards and bigger risks, tied together and inseparable; low leverage means a steadier, more forgiving ride. Neither is good or bad on its own — but knowing which one you're looking at is the difference between reading a quarter and being blindsided by it.
Valarn is an educational research tool, not investment advice. It does not tell you to buy, sell, or hold anything, and nothing here is a recommendation or a promise of results. Always do your own research and consider consulting a licensed financial professional.
Valarn
Research
Valarn Research Team
